Russia's Machine Tool Output Rose 21.5% in January–April 2024: What Stands Behind the Growth
Machine tool production in Russia reached 18.6 thousand units in January–April 2024, which is 21.5 percent more than in the same four months of 2023, according to a report by the HSE Institute for Statistical Studies and Economics of Knowledge (ИСИЭЗ ВШЭ) covered by the Expert outlet on June 27, 2024. The institute's review spans 43 product types of the machine tool industry, and its headline figure — a fifth of additional output within a single year — is among the strongest annual growth rates to appear in recent statistical publications on the sector. Yet the same dataset that produces the impressive headline also contains the reasons for caution: the composition of the growth, the absolute size of the high-technology segments and the way robotics output is measured all point to an expansion that is broad in units but narrow in technological depth.
This article unpacks the published set: the total and what it implies about the comparison base, the six structural categories the report names, the two point accelerations it highlights, and the monetary figures for industrial robots and robotic complexes. It then asks what could plausibly stand behind a 21.5 percent gain — a low base, import substitution, state defence-related demand — and why the structure of output limits any technological conclusion drawn from the headline number alone.
The headline: 18.6 thousand machines, up 21.5 percent
The core fact of the report is compact. In the four months from January through April 2024, Russian manufacturers produced 18.6 thousand machine tools across the 43 product types the institute tracks. Measured against January–April 2023, that is an increase of 21.5 percent. Two features of this pairing deserve attention before any interpretation begins.
First, the growth rate is annual, not monthly and not accumulated over several years: it compares one four-month window with the immediately preceding four-month window. A 21.5 percent year-on-year gain over a third of a year is a fast pace by the standards of any capital goods industry, where order books, installation cycles and commissioning normally stretch adjustments over considerably longer horizons.
Second, the arithmetic behind the percentage is modest in absolute terms. If 18.6 thousand units represent a 21.5 percent increase, the comparison base of January–April 2023 works out at roughly 15.3 thousand units, meaning the gain is on the order of 3.3 thousand additional machines over four months. That is a meaningful addition for a sector of this size, but it is also a reminder that double-digit percentages in machine tooling are computed on bases measured in thousands, not hundreds of thousands, of units. The same percentage in an industry with a million-unit base would describe a different economic event entirely.
A four-month window: what it can and cannot show
The published period is January–April, a third of a calendar year. Such a window has analytical advantages and limits that are worth stating explicitly. Its advantage is timeliness: four-month totals appear well before annual yearbooks, and they capture turning points in output earlier than any full-year figure could. Its limit is volatility: a four-month aggregate can be moved by the delivery schedule of a few large contracts, by the timing of a plant's restart, or by the shift of a single order batch between quarters, none of which changes the underlying capacity of the industry.
For that reason, a 21.5 percent four-month gain is best treated as a strong signal rather than a settled trend. It says that something changed in the flow of finished machines between the first third of 2023 and the first third of 2024. It does not, by itself, say whether that change is a step to a permanently higher plateau, a catch-up after a weak period, or the front-loading of orders that will not repeat in the second half of the year. The report reviewed here contains no monthly series and no forecast, so the dataset supports description of the window, not extrapolation beyond it.
Forty-three product types behind one number
The 18.6 thousand figure is not a count of a single machine class. The institute's review covers 43 product types of machine tool manufacturing, and the published total aggregates all of them. That breadth matters for two reasons.
On the one hand, it means the headline growth is not the artefact of one niche product line doubling from a tiny base: with 43 types in the basket, a 21.5 percent aggregate implies that increases were spread across a substantial part of the product range. On the other hand, an aggregate of 43 heterogeneous types — from simple woodworking saws to numerically controlled turning machines — cannot by itself say anything about which technologies carried the increase. For that question, the report's structural breakdown is needed.
The structure of output: six named categories
Of the 43 types reviewed, the report names six categories with their January–April volumes. In descending order of output, they are:
- other metalworking machine tools — 3.4 thousand units;
- metal-cutting machine tools — 2.9 thousand units;
- woodworking machine tools — 2.4 thousand units;
- turning, boring and milling machines — 1.8 thousand units;
- deburring, sharpening, grinding and other finishing machines — 1.2 thousand units;
- woodworking circular-saw, band-saw and jigsaw machines — 1.1 thousand units.
Read as a list, the structure has a clear centre of gravity. The two largest named positions are the residual "other metalworking" group and the general metal-cutting class; woodworking appears twice, once as a general class and once as the sawing subgroup, and taken together the woodworking entries rival the metal-cutting line. The categories that describe precision work on metal — turning, boring and milling on one line, grinding and finishing on another — sit in the middle and lower part of the list.
A simple addition of the six named volumes gives 12.8 thousand units, or roughly seven tenths of the 18.6 thousand total; the remaining three tenths are distributed across the other product types among the 43 that the report does not itemise. The addition should be treated as indicative rather than exact, because the named lines may sit at different levels of aggregation — a sawing subgroup, for instance, can plausibly be part of the woodworking class rather than an addition to it. What the list shows beyond doubt is the ranking itself.
What the ranking implies
The ranking places simple and general-purpose equipment at the top of the structure and reserves the smaller volumes for the categories associated with higher technological content. Nothing in the report criticises that shape: an industry serves the demand it has, and demand for sawing, grinding and general metalworking machines is real and large. But the shape does mean that the sector's unit volume is carried predominantly by equipment whose production does not require the competencies of high-precision engineering — competencies that are usually the actual subject of a modernisation debate.
Point accelerations: sawing machines and CNC turning
Beyond the aggregate, the report highlights two category-level growth rates, and they point in instructively different directions.
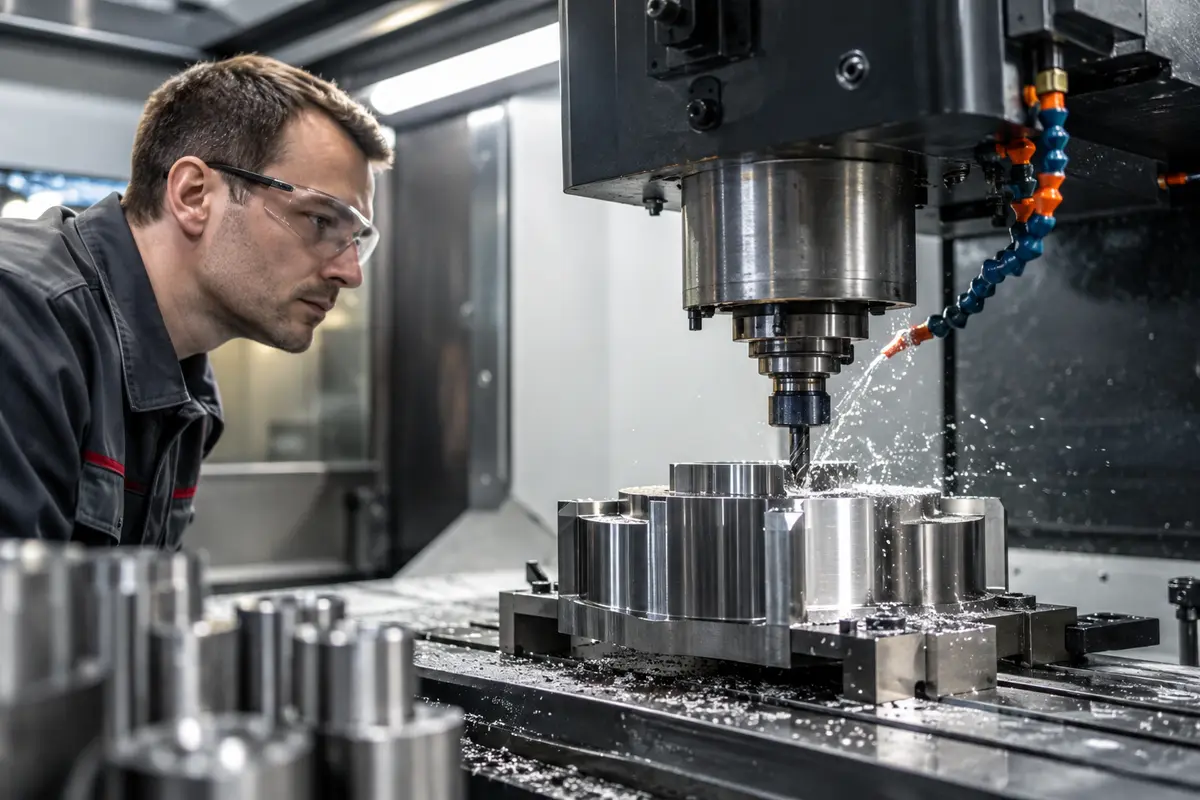
The faster of the two among the volume categories is woodworking circular-saw, band-saw and jigsaw machines, up 31.6 percent year on year to 1.1 thousand units. This is the simplest equipment in the named structure — sawing machines for timber and board materials — and its growth rate exceeds the sector average by a wide margin. A third of additional sawing machines in four months describes demand for basic processing capacity, not for advanced manufacturing technology.
The second highlight is the one that attracts the most attention in technology discussions: metal-cutting turning machines with numerical control, up 50.6 percent year on year. A 50 percent gain sounds like a breakthrough — until the absolute figure is placed next to it: 309 units. Three hundred and nine CNC turning machines in four months, even after a half-again increase, is a volume measured in hundreds. Set against the 18.6 thousand total, the CNC turning line accounts for roughly one and a half to two percent of all machine tools produced in the period; set against the 1.8 thousand turning, boring and milling machines of all control types, it remains a minority of its own class.
The contrast between the two highlights is the analytical heart of the dataset. The category growing at 31.6 percent adds hundreds of simple machines; the category growing at 50.6 percent adds roughly a hundred sophisticated ones. Both growth rates are real and both are reported by the same institute, but they describe different industries hiding inside one aggregate number.
Robots measured in roubles, not units
The report's robotics figures complete the picture, and they do so in a different unit of measurement altogether. For January–April 2024, the output of industrial robots is given as 32.7 million roubles, and the output of robotic complexes as 26.1 million roubles. No unit counts are published for either category in the set reviewed here.
Two observations follow. First, the switch from units to money is itself informative: where volumes are too small or too heterogeneous to aggregate meaningfully in pieces, statistical practice moves to value terms. A segment producing thousands of machines reports units; a segment whose four-month output fits into tens of millions of roubles reports money. Second, the scale is small. Combined, the two robotic lines amount to 58.8 million roubles of output over four months — a figure that, in the context of a national machine-building industry, describes a nascent segment rather than an established one. The report thus places robotics alongside machine tools not as a second engine of growth but as a footnote-sized complement to it, and any narrative of mass automation of Russian factories would need a dataset of a different order to stand on.
The choice of unit also shapes the comparison with machine tools. Eighteen thousand six hundred machines and 58.8 million roubles of robotics output belong to different measurement regimes; placing them side by side in one article is legitimate only because the report itself publishes them side by side, and the reader should keep in mind that the rouble figures say nothing about how many robots or complexes were actually completed, installed or shipped in the period.
What could stand behind a 21.5 percent gain
A growth rate of this size invites explanation, and the published set itself offers none: the institute reports volumes and rates, not their causes. Three candidate explanations are usually discussed for expansions of this shape, and each remains a hypothesis against this dataset.
- A low comparison base. If January–April 2023 was itself a weak period — roughly 15.3 thousand units by the implied arithmetic — then part of the 21.5 percent is recovery rather than expansion: the same absolute addition produces a larger percentage on a smaller base.
- Import substitution. Where foreign supply of machine tools has contracted, domestic producers can gain volumes by occupying vacated niches without any change in the technological level of their products; such substitution would show up exactly as this dataset shows it — in units of general-purpose and simple equipment first.
- State and defence-related demand. Order flows financed from public budgets can lift output of specific categories quickly and independently of private investment cycles; a demand-led surge of this kind would also become visible in units before it appears in any technological indicator.
None of these three can be confirmed or rejected from the published figures: the report contains no base-year commentary, no import data and no breakdown by customer type. What the dataset can do is constrain the hypotheses. A substitution- or order-driven expansion would be expected to concentrate in the categories where domestic producers already have serial capacity — precisely the simple and general-purpose lines that dominate the structure. A technology-driven expansion would be expected to show up first in the absolute volumes of CNC equipment and robotics — precisely the lines that remain at 309 units and tens of millions of roubles. The structure of the growth, in other words, is more consistent with the first group of explanations than with the second, even though the report itself does not adjudicate between them.
There is a fourth, quieter possibility that the dataset neither supports nor excludes: that the gain is a statistical composition effect, with several mid-sized categories growing moderately at the same time and none of them dominating. In a basket of 43 types, such a broad-based, medium-tempo advance would produce exactly the aggregate seen here while leaving every individual highlight modest. The two point accelerations the report names — 31.6 and 50.6 percent — are the only category-level rates published, so the behaviour of the remaining types stays invisible, and the composition effect remains untestable from this source.
Why the structure limits the technological reading
The temptation in reading this dataset is to convert "plus 21.5 percent" into "the machine tool industry is modernising". The structure of output blocks that conversion at three points.
The first is composition. The top of the named structure consists of residual and general-purpose categories and of woodworking equipment; the precision-metalworking lines sit below them. Growth led by the top of the structure increases the count of machines without changing the technological profile of the fleet being produced.
The second is the absolute size of the advanced segments. Numerically controlled turning machines — the flagship category of any modernisation narrative — number 309 units for the period. Even a 50.6 percent growth rate leaves that category at a scale where a single plant's commissioning schedule can move the national percentage. Percentages computed on bases of a few hundred units are volatile by construction; they are poor evidence of a structural shift.
The third is measurement. Robotics, the segment that would most directly signal automation of production, is reported in roubles: 32.7 million for industrial robots and 26.1 million for robotic complexes. Value terms at this scale cannot support unit-based conclusions about the diffusion of automation into factories; they document existence, not deployment.
Taken together, these three limits do not diminish the reported achievement — an additional 3.3 thousand machines in four months is real output — but they relocate it. The dataset describes quantitative recovery and expansion of a broad, mostly conventional product range. It does not yet describe a technological transition, and any claim that it does would require evidence the report does not contain: unit volumes of CNC equipment an order of magnitude higher, robotics output measured in thousands of installations, or a visible shift of the named categories toward the precision end of the structure.
Conclusion
The January–April 2024 figures from the HSE Institute for Statistical Studies and Economics of Knowledge describe a machine tool industry growing fast in units: 18.6 thousand machines across 43 product types, 21.5 percent above the same period of 2023, with sawing machines up 31.6 percent and CNC turning up 50.6 percent to 309 units, and robotics output of 32.7 and 26.1 million roubles. The same figures, read structurally, describe where that growth sits: in general-purpose and simple categories at the top of the list, in hundreds rather than thousands of units at the technologically advanced end, and in monetary terms where automation is concerned. The double-digit headline is therefore best read as evidence of a broad quantitative expansion — plausibly base-, substitution- or order-driven — while the technological conclusion remains open, pending volumes that the current structure of output does not yet show.
Leave a comment